



Frozen pipe coverage is the part of your homeowners policy that pays for sudden water damage after a pipe freezes and bursts, and it comes with conditions most owners never read. According to the Insurance Information Institute, water damage and freezing made up 22.6% of all U.S. home insurance claims in 2023, with an average claim near $15,400. Check these seven details before December. The Private Risk Management Association adds that water claims remain the largest source of loss for private clients, as reported by Insurance Business.
Winter claims surprise owners because the policy language rarely gets read until the loss has happened. This list moves that reading to November.
1. Heat and Vacancy Conditions in Your Frozen Pipe Coverage
Many policies expect the heat to stay on. If a second home sits empty for more than a set number of days, or the thermostat was off, the insurer may limit or deny a freeze claim. Ask what your policy requires and how long a home can sit unoccupied. Seasonal and second homes face the greatest risk, because a failed furnace can go unnoticed for days.
2. Gradual Leaks and Seepage
Coverage generally applies to sudden and accidental events. A slow leak behind a wall that runs for weeks may fall under an exclusion for continuous seepage. Insurers often ask when the leak began, so keep records of inspections and maintenance.
3. Water Backup and Sump Failure
Water that backs up through a drain or overflows a sump pump usually needs a separate endorsement. It is inexpensive relative to the exposure, and it is easy to add. A finished basement with high-value contents widens the gap.
4. Ice Dam Removal
Interior damage from an ice dam is often covered, while the cost of removing the dam itself may not be. Ask how your policy treats both. Proper attic insulation and ventilation reduce the odds of a dam forming, and a roof inspection in November costs little.
5. Water Damage Deductibles
Some policies use a separate or percentage deductible for water losses. On a high-value home, that can mean a five-figure out-of-pocket cost before coverage starts. Ask for that deductible in dollars, based on your home’s actual value. Our home insurance specialists can show you where yours sits.
6. Tear-Out and Access Costs
Reaching a burst pipe often means opening walls and floors. Some policies pay for the resulting damage but exclude the cost of repairing the pipe or the access work. Confirm which applies, and ask whether custom finishes such as cabinetry or stone floors are repaired to their original quality.
7. Additional Living Expense Limits
A major water loss can push a family out of the house for months. Additional living expense coverage is capped by dollar amount or time, and finish work on a high-end home can take longer than the cap allows. Compare the cap to a realistic rebuild timeline.
Frequently Asked Questions
Does homeowners insurance cover a burst pipe?
Usually it covers sudden and accidental damage from a burst pipe, subject to your deductible and policy conditions.
Do leak sensors lower risk?
Yes. Automatic shutoff valves and leak sensors limit the volume of water and the size of a claim, and some carriers offer a discount for them. Our Private Client Group can recommend options for higher-value homes.
What should I do first when a pipe bursts?
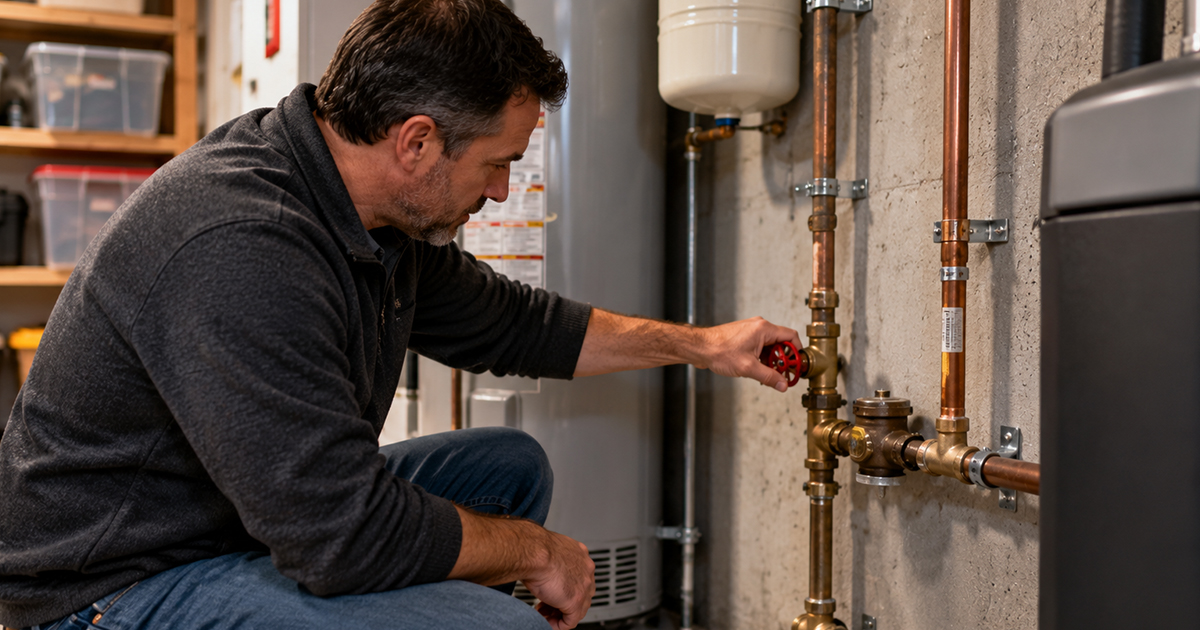
Shut off the main water valve, turn off electricity to affected areas if it is safe, photograph the damage, and call your insurer promptly.
Read the freeze language in your policy this month, because a few days of attention now decides what a burst pipe costs you in January.
The renewal lands on the CFO’s desk in late October: another double-digit increase on the fully insured plan, the third in four years. The company has 150 employees, a fairly young workforce, and a hunch that it is paying for other employers’ claims. So the CFO asks a simple question. Would a self-funded health plan cost less?
A self-funded health plan pays employee claims directly from company funds, usually through a third-party administrator, with stop-loss insurance to cap large losses. Self-funding is mainstream. The KFF 2026 Employer Health Benefits Survey found 71% of covered workers are in self-funded plans, including 85% at firms with 200 or more workers. At firms with 10 to 199 workers the figure is 25%, and 38% of covered workers at those firms are in level-funded plans, a hybrid built on the same idea. SHRM’s 2026 benefits survey also found self-insured plans more common this year than last.
How the Money Moves in a Self-Funded Health Plan
Costs fall into two buckets. Fixed costs include the administrator’s fees, network access, and stop-loss premiums, and they are paid every month regardless of claims. Variable costs are the claims themselves, which rise and fall with how the workforce uses care. In a good year, money that would have gone to an insurer stays with the company. In a bad year, the company pays more, up to the limits its stop-loss coverage sets.
The Two Stop-Loss Layers That Define the Risk
Specific stop-loss caps what the company pays for any one person. With a $75,000 specific deductible, a $400,000 cancer claim costs the company $75,000 and the stop-loss carrier covers the rest. Aggregate stop-loss caps total claims for the year, often at around 120% to 125% of expected claims. Together the two layers define the worst case the CFO has to plan for.
Those layers matter more each year. Cancer was the top cost driver named by 70% of employers in the Business Group on Health survey for 2027, and a single specialty drug or gene therapy claim can now exceed $1 million.
Running the Scenario for 150 Employees
Here is an illustrative example, with round numbers chosen to show the mechanics. Suppose the fully insured renewal quotes $2.4 million. A self-funded quote might show $400,000 in fixed costs and $1.8 million in expected claims, for an expected total of $2.2 million. With aggregate stop-loss at 125% of expected claims, the maximum claims liability is $2.25 million, so the worst case reaches $2.65 million.
That spread is the decision. In an average year the company saves about $200,000. In a very bad year it pays about $250,000 more than the insured renewal would have cost. A company with steady cash flow and a multi-year view can usually absorb that range. A company that would struggle to fund one bad quarter of claims should think carefully before switching.
Questions to Answer Before You Switch
- Cash flow: Can the company fund claims as they arrive, including a few unusually heavy months?
- Run-out: Who pays claims incurred during the final plan year but submitted after the contract ends?
- Lasering: Can the stop-loss carrier set a higher deductible for a known high-cost member at renewal?
- Data: Will you receive monthly claims reports detailed enough to manage the plan?
- Compliance: Do you have a plan document, a summary plan description, and a clear understanding of your fiduciary duties?
Middle Paths Worth Pricing
Level-funded plans give smaller employers a fixed monthly payment that feels like a premium, often with a partial refund when claims run low. KFF notes these plans may use health status in underwriting, so a group with a few known conditions may see less favorable pricing. Group captives let mid-sized employers pool stop-loss risk with similar companies, smoothing results over several years. Our captive insurance solutions team can price both options alongside a conventional self-funded quote, and our data analytics and benchmarking team can test them against your actual claims history.
Back to the CFO’s Question
So would a self-funded health plan cost less for the 150-employee company? In most years, probably. In a bad year it could cost more, by an amount the CFO can now see on paper. The real question becomes whether the company can live comfortably with the worst case. Answering it takes a few weeks of claims analysis, which is why the conversation belongs in November, well ahead of the next renewal deadline. Tooher-Ferraris will run the numbers with your own claims data so the 2027 decision rests on your experience.
A liquidity event, such as selling a business or cashing out equity, can change a household’s net worth in a single day and leave its insurance program exactly where it was. Insurance planning after a liquidity event means rebuilding five layers of protection around a larger balance sheet. Coordinate each layer with your CPA and estate attorney.
Insurance Planning After a Liquidity Event: The Five Layers
Work through the layers in order, because each one builds on the last.
Layer One: Liability
More assets create a larger target for a lawsuit. Umbrella limits that made sense at a lower net worth often fall short afterward. Review umbrella and excess liability limits against your new total assets and future earning power. Confirm that the umbrella sits above every underlying policy and that those policies meet its minimum limits. Our Private Client Group builds these layers for households in transition.
Layer Two: Property and Valuables
New purchases tend to follow a sale: a larger home, a second residence, art, jewelry, collector vehicles, or a boat. Standard policies cap many of these categories. Confirm replacement cost values on every property and schedule high-value items individually. Keep an updated inventory with photographs, because a larger home with new furnishings can leave an old contents limit far behind.
Layer Three: Life Insurance and Estate Liquidity
The IRS federal estate tax exemption for 2026 is $15 million per person, or $30 million per couple, with a 40% rate on amounts above it. Annual gifts are excluded from gift tax up to $19,000 per recipient. A household near or above those thresholds can face a tax bill due in cash while most of its wealth sits in illiquid assets. Permanent life insurance can supply that cash so heirs do not have to sell assets under pressure. Review existing coverage through our life insurance team, and ask your estate attorney how any policy should be owned.
Layer Four: Digital and Identity Exposure
A public sale, a press mention, or a published transaction price raises your profile. Higher visibility can invite fraud, impersonation, and targeted cyber attacks on family members. Review cyber and identity theft coverage and tighten account security across the household, including the accounts of adult children and aging parents. The Federal Trade Commission’s IdentityTheft.gov offers recovery steps if an account is compromised.
Layer Five: Transition Coverage
Employer-provided benefits often end at closing. Confirm health coverage continues without a gap, replace group life insurance that ends with the job, and ask your corporate counsel whether the sale agreement requires you to maintain tail or run-off coverage for the business you sold. Plan these moves before closing, since several end on the closing date.
Frequently Asked Questions
When should I update my insurance after selling a business?
Start before closing. Several coverages end on the closing date, and replacement coverage should be in place the day they stop.
Do I still need an umbrella policy after a sale?
Usually yes, and often a larger one. Liability exposure follows your assets and your public profile.
How often should I review coverage after the sale?
Review at six and twelve months, and after every major purchase or family change.
What to Watch Over the Next 12 Months
The estate tax exemption is indexed to inflation, so the thresholds will move each January. Every major purchase, new property, or change in family structure should trigger a quick coverage check. Plan for a full review at the six-month and twelve-month marks after the event, when new assets are in place and your advisors have a clear picture.
Most households that do this well treat it as a project with a calendar, and they bring their insurance advisor to the table alongside the CPA and the attorney.